








The data center developer also plans to exchange some of its older debt for shares. The new offering is scheduled to close on October 16, subject to closing conditions.
Data center developer Cipher Digital (CIFR) has priced an $850 million offering of unsecured convertible notes carrying no regular interest payments and maturing on November 1, 2032. The private sale to qualified institutional buyers is scheduled to settle on October 16, 2026, subject to customary closing conditions.
Cipher announced the proposed sale on October 13. Under the terms released on October 14, initial purchasers have a 13-day option to buy up to another $150 million of notes. Exercising the option in full would take the total principal amount to $1 billion.
Initial conversion price set at $15.31
The initial conversion rate is 65.3211 shares for each $1,000 of principal. That implies a conversion price of about $15.31, a 35% premium to Cipher’s October 13 closing share price of $11.34. When conversion conditions are met, Cipher can choose to settle in cash, shares or a combination of both. The conversion rate may be adjusted following certain events.
Cipher expects about $835.1 million in proceeds after the initial purchasers’ discounts and commissions, but before its own estimated offering expenses. It plans to use $89.7 million to pay for capped call options entered into alongside the pricing.
The options are designed to reduce potential dilution from conversion or offset cash payments above the converted notes’ principal, subject to a limit. Their initial cap price is $28.35. The protection is limited, and the cap is a contract term rather than a share-price forecast or promised return.
Zero coupon does not mean cost-free funding. Cipher will still incur discounts, commissions and option costs. Conversion into shares could also reduce existing shareholders’ percentage ownership.
Older debt may be exchanged for 40.7 million shares
In a separate transaction alongside the new offering, Cipher expects to exchange about $165.9 million of its 1.75% convertible notes due in 2030 for common shares. The total consideration, including accrued interest, is expected to be roughly 40.7 million shares. The debt-for-equity exchange is separate from the cash the company plans to raise through the new notes.
Holders of the new notes will also have a cash repurchase right before the 2032 maturity. Unless Cipher has already called all outstanding notes for redemption, holders can require a cash repurchase on November 1, 2030. The company’s own early redemption right, available from 2029, depends on specified share-price and other conditions.
Funding for Barber Lake and the development pipeline
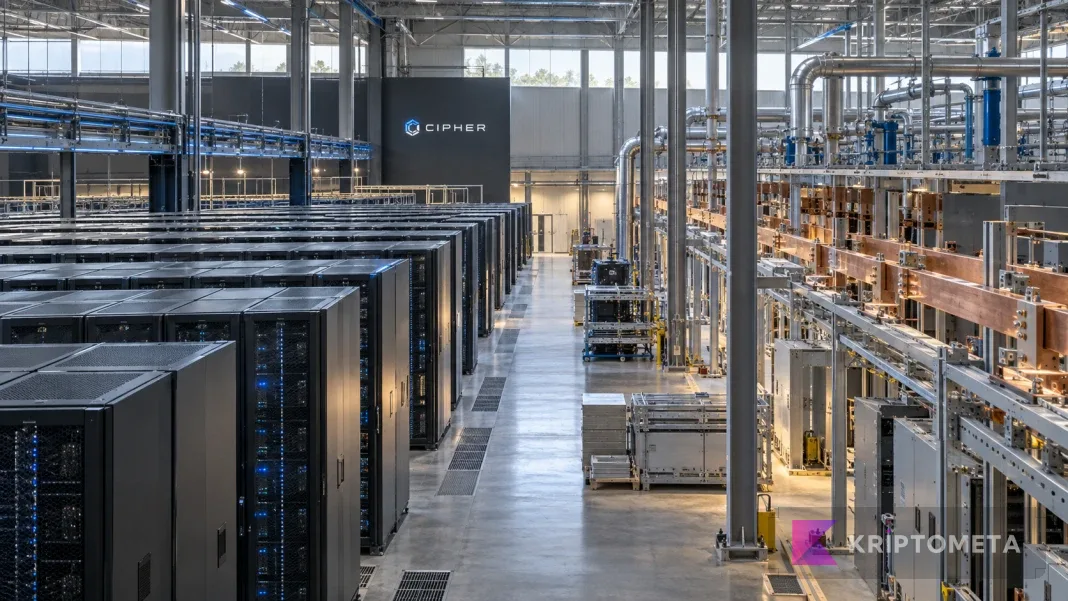
After the option costs, Cipher plans to use the remaining proceeds for additional equity investment in Barber Lake, near-term high-performance computing (HPC) projects, new development sites and general corporate purposes. It did not disclose how much would go to each project.
In its September 25 Barber Lake announcement, Cipher said the Texas project’s lease term had been extended from 10 to 20 years, taking total contracted revenue from $3.8 billion to more than $9 billion. Those figures describe revenue expected over the contract periods, not cash collected upfront.
Individual data halls at Barber Lake are scheduled for phased delivery from the fourth quarter of 2026 through the first quarter of 2027. Rent will begin as each hall is delivered, with the first rent commencement targeted for late 2026.
Cipher Digital’s September 25 Barber Lake announcement
The post loads from X when you open it.